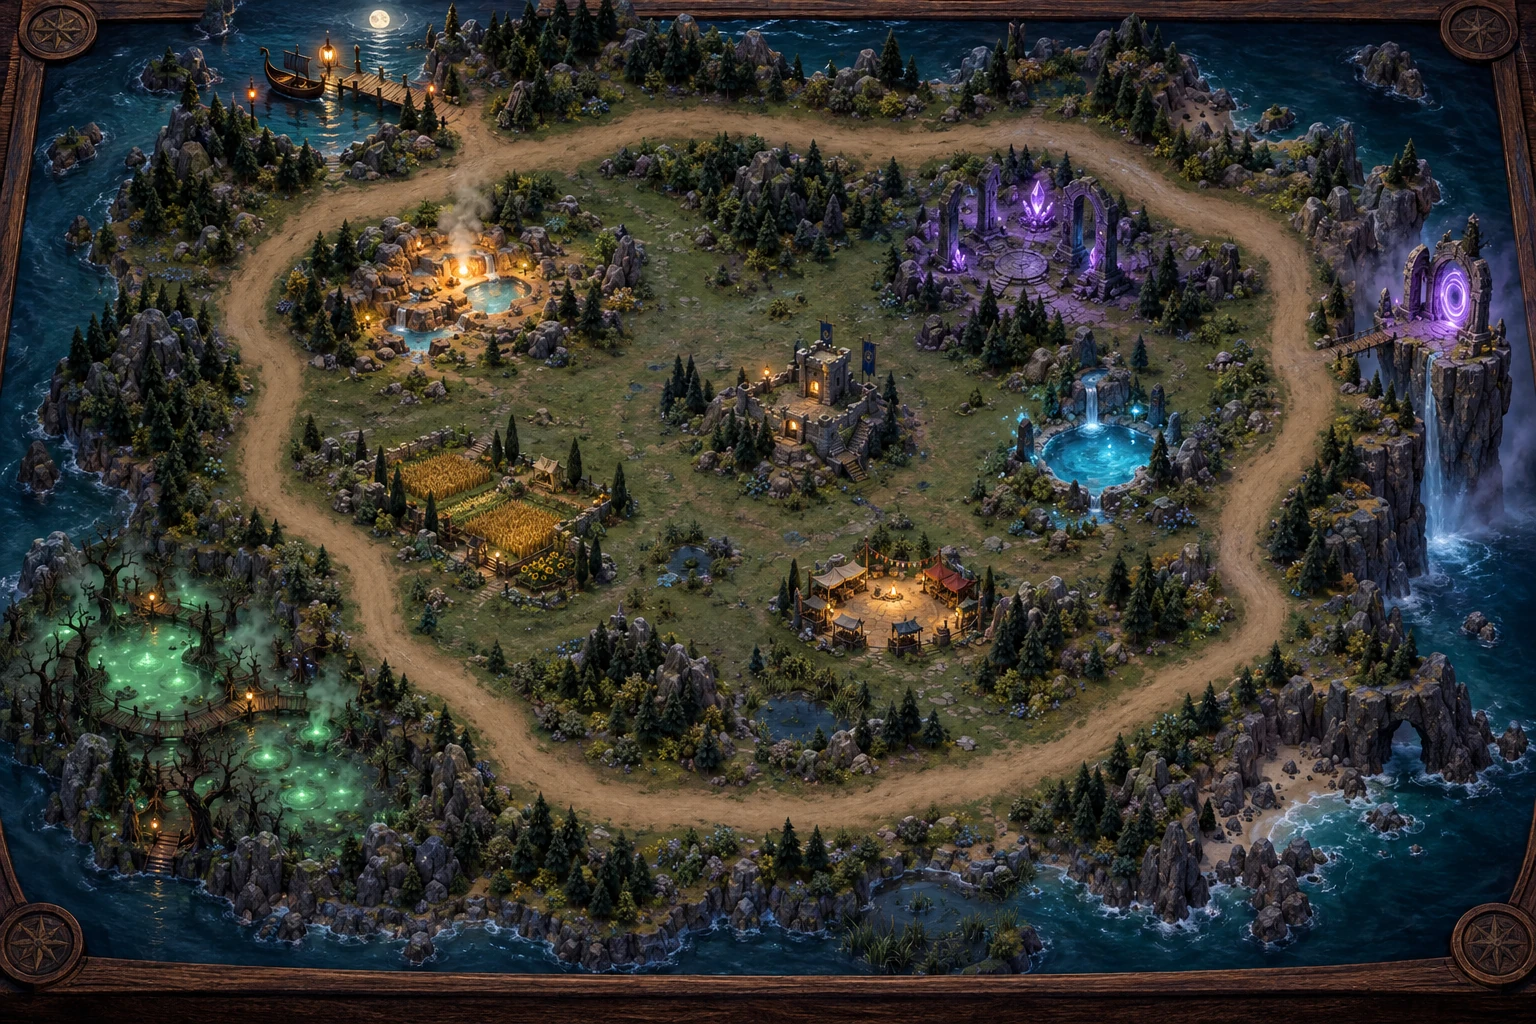
A realm of little choices.
Coffee warms the springs. Groceries feed the gardens. Each day brings another step along the gilded trail.
Imported statements, budgets, and merchant choicesstay in this browser · never uploaded.
Budget Satchel
Don’t trust it’s truly private? Run your own copy on your computer—even offline if ya like!
Windows launcher included · Mac/Linux: Python 3 + a browser. No saved statements included.Tap a tile or a realm to explore
Coffee warms the springs. Groceries feed the gardens. Each day brings another step along the gilded trail.
Imported statements, budgets, and merchant choices